To view this letter in PDF Format please click here: 2026-Q3 PBCM Investor Letter
Welcome to our new investors and thank you to our existing clients and partners for your continued support. We are pleased to present our results for the most recent quarter in the following pages.
After reading this letter, please do not hesitate to contact us if you have any questions, want to discuss any topics in greater detail, or would like to learn more about our Concentrated Value portfolio. We can be easily reached via e-mail at info@pelicanbaycap.com. We welcome your feedback and look forward to your correspondence.
The third quarter was a tale of two halves. The portfolio roared out of the gate, advancing 7.8% across July and August and allowing us to claw back some of the underperformance relative to the Russell 1000 Value Index from the second quarter. As noted in our previous letter, we remain confident in our Concentrated Value strategy holdings: high-quality companies with robust cash flows, defensible business models, and strong balance sheets that trade at substantial discounts to our estimate of their intrinsic value.
However, momentum reversed in September as the portfolio fell 8.1%, erasing our relative lead. This downturn occurred despite a lack of negative earnings reports or corporate announcements from our holdings; instead, performance was driven by broader negative momentum factors. As a portfolio manager, this disconnect was deeply frustrating.
Ultimately, the portfolio closed the quarter down -0.9%, trailing the Russell 1000 Value Index’s 2.6% gain. The underperformance was primarily driven by weakness in homebuilding-related stocks as interest rates spiked in September, though this was partially offset by gains in our energy and software holdings.
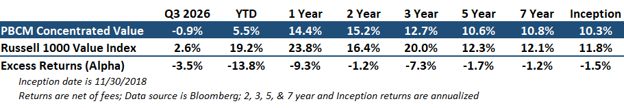
Our biggest winner this quarter was Corpay (CPAY), which is also the portfolio’s largest position. The company continues to execute its transition from a predominantly fuel card operation toward a broader corporate payments focus. FactSet (FDS) also performed well in the third quarter as it continued to grow and ease market concerns regarding the impact of artificial intelligence (AI) on its business model. We believe companies that control valuable datasets, like FactSet, are poised to benefit from AI. Those initial AI concerns provided us the opportunity to initiate our position last December; please refer to our Q4 2025 investor letter for our full investment thesis on the company.
Strength in commodity prices—particularly energy—boosted both Barrick Mining (B) and Devon Energy (DVN). We continue to believe that oil prices will stay higher for much longer than the market is pricing into futures contracts. Global oil inventories have fallen significantly since the Iran conflict began in March, and we anticipate that global oil demand will exceed supply for several years unless a major global economic slowdown occurs in the near future.
You can find a complete list of the portfolio’s top contributors and detractors for the second quarter of 2026 in the table below.
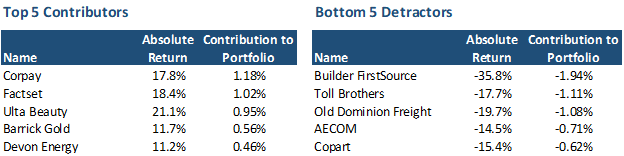
On the negative side, investors appear to be throwing in the towel on homebuilding-related stocks as rising interest rates have pushed mortgage rates back above 7%, and housing affordability issues receive widespread mainstream media coverage. Builders FirstSource (BLDR), a supplier to homebuilders, was our largest detractor from performance this quarter. Similarly, Toll Brothers (TOL) fell about 18% during the period. Toll has been one of the better performers in the housing sector because it serves the luxury market, where many buyers pay cash and high mortgage rates pose less of a barrier.
AECOM (ACM) also continued to experience share price weakness. This quarter, the company delivered a disappointing earnings report showing that it still had two large legacy construction contracts remaining. As you may recall from our Q4 2025 letter, AECOM is a major construction and engineering firm that has been eliminating its riskier, more volatile construction operations to transition into a pure-play engineering and design firm. Unfortunately, these two legacy projects experienced delays and cost overruns, resulting in a surprise loss for the quarter. Management confirmed that no other large legacy construction contracts remain, and we added to our position on this weakness.
Turning to other portfolio activity, we trimmed Corpay and Royalty Pharma (RPRX) on strength as both stocks approached the upper end of our fair value estimates. Additionally, we consolidated our energy exposure by trimming Diamondback (FANG) and EOG Resources (EOG) while boosting Devon Energy (DVN). We made this adjustment to reduce overall energy exposure while increasing our weight in Devon, which was undervalued relative to both EOG and FANG. Lastly, we initiated a new position in Copart (CPRT).
Copart is the dominant player in the salvage auto auction industry, holding roughly 60% of the U.S. market share as part of a rational duopoly. Copart acts as a critical service provider for auto insurance carriers, handling everything from towing logistics and complex state-specific DMV titling to running digital auctions across 281 yards spanning 21,000 acres. Salvage vehicle auctions and associated buyer fees drive 85% of revenues, supported by a global buyer base of over 1 million members in 185 countries that consistently delivers maximum auction yields for insurance carriers.
The stock has come under recent pressure due to a perfect storm of cyclical headwinds, margin compression, and short-term market share concerns. A drop in used car prices from their 2022 highs weighed on average vehicle values and percentage-based auction fees. At the same time, auto insurance premiums surged 10–15%, pushing the rate of uninsured drivers in the U.S. up to 14% and temporarily suppressing salvage claims volume. Wall Street was further spooked by a slight, temporary market share loss to primary competitor IAA that was driven by rapid market share growth at Progressive (where IAA holds an 80% of the salvage auction business) and the loss of a single, low-margin insurance account while heavy catastrophe processing costs from severe weather temporarily squeezed EBIT margins.
Despite these transient issues, Copart’s core business model remains exceptionally high-quality with massive competitive moats. Unlike its main competitor, Copart’s long-standing strategy of purchasing and owning its salvage yard real estate near major metropolitan centers creates a durable barrier to entry. Furthermore, the company maintains a pristine balance sheet with $4.1 billion in net cash ($4.35 per share, or 13% of its market capitalization), providing downside protection, capital flexibility, and funding for strategic acquisitions like Purple Wave to expand into heavy industrial equipment.
Looking ahead, favorable structural industry Tailwinds remain firmly intact, including an aging U.S. vehicle fleet, rising total loss frequency (which has climbed from 16% to 23%), moderating insurance inflation, and stabilizing used car prices. Additionally, legendary CEO Jay Adair, who spearheaded Copart’s transformation from 2010 to 2022, has returned to the helm. Owning 3% of the company, his interests are directly aligned with shareholders as he acts swiftly to stem carrier market share loss and drive expansion.
As international operations continue to scale toward U.S. profitability levels and domestic volume recovers, top-line growth should return to the upper single digits. Combined with inherent operating leverage and opportunistic share repurchases, we believe Copart is positioned to compound earnings per share in the 8–14% range over the medium term resulting in normal earnings power of $1.75–$2.00 per share.
Applying a 20–25x valuation multiple—appropriate for a high-quality compounder with a wide moat, net cash balance sheet, and double-digit growth profile—and adding back $4.35 per share in net cash results in an intrinsic value range of $40–$55 per share. Trading at a cyclical discount, Copart represents a compelling opportunity to own a world-class business at an attractive risk-adjusted entry point. We acquired our shares for $32 per share.
Lastly, we wanted to revisit the Investment Philosophy of the Concentrated Value portfolio. We utilize a value investment strategy that seeks out companies for investment which the Portfolio Manager deems to be high quality companies. Quality is defined by possessing business operations with durable competitive advantages, allowing for high returns and growing cash flows streams. We want these high-quality companies to also have solid balance sheets, preferably with a net cash position. We also prefer that their management teams make decisions with an emphasis on maximizing shareholder returns.
Once we find these high-quality companies, we generally only invest in their stock if they trade at a steep discount to our estimate of their intrinsic value. This is necessary to provide our investors with the opportunity to generate an above-market return and protect capital. This discipline creates a wide margin of safety if an undesirable scenario plays out in the future. Pelican Bay Capital Management believes that identifying a significant difference between the daily market value of a security and the intrinsic value of that security is what defines an investment opportunity.